Multifamily developers become more selective as markets diverge
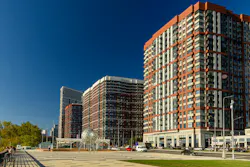
Multifamily developers are becoming more selective about where they deploy capital as apartment-market conditions increasingly vary by geography.
Thompson Thrift, for example, launched a new multifamily development partnership targeting $200 million to $230 million in capital commitments for six Class A communities across Colorado, Kentucky, Arizona, Nevada, and Montana. The partnership represents the developer's ninth multi-project development vehicle and includes its first multifamily project in Montana.
Earlier this week, Multifamily Dive reported that the firm views access to repeatable institutional equity as an advantage in the current market.
That selective approach comes as the broader development pipeline continues to face pressure. The National Multifamily Housing Council's September survey found that 29% of respondents had started fewer projects than three months earlier. Rather than repeating the survey's findings on labor and material costs, the data point to a broader shift in which developers are weighing market fundamentals and project feasibility more carefully before committing capital.
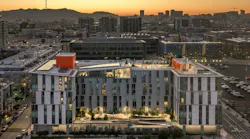 Photo: Patrick Argast, courtesy Mithun
Apartment Demand Varies Sharply by Market
Recent Yardi Matrix September multifamily market reports illustrate why location is becoming an increasingly important consideration. In its Chicago Multifamily Market Report, Yardi found that average advertised asking rents rose 0.4% on a trailing three-month basis through July, twice the national rate, while June occupancy remained near 96% despite a robust development pipeline.
By comparison, Yardi reported that Phoenix rents fell 2.1% year over year through July, with occupancy at 93.2%, while Denver rents were essentially flat on a trailing three-month basis and remained under pressure from roughly 18,000 units still under construction.
The contrast suggests that the national multifamily market is becoming less useful as a single measure of development conditions. Markets with strong renter demand and limited competitive supply can continue to support new projects, while developers in markets still absorbing large waves of deliveries may have greater incentive to delay starts or pursue existing properties instead.
For architects, engineers, and contractors, that divergence could make market selection, project positioning, and capital structure increasingly important to multifamily development. Developers with access to institutional equity may continue moving forward in markets where rents and occupancy support new construction, while other opportunities may shift toward acquisitions, rehabilitation, preservation, or adaptive reuse.
About the Author
 BD+C Staff
The Building Design+Construction editors bring you all things related to the AEC market, from the latest design tools to green building trends.
BD+C editors include David Barista, Editorial Director; John Caulfield, Senior Editor; and Quinn Purcell, Managing Editor.